 EN
 PT


Head Offices:
Hotline: (877) 289-6429
Working Hours:
Monday to Saturday 6:00 AM – 7:00 PM, Sunday Closed
Website: https://mrmsteel.ai/
The steel industry has long been considered the backbone of global industry and infrastructure, as steel is widely used in construction, transportation, machinery manufacturing, and infrastructure projects. Understanding global steel production and consumption not only helps investors, steel companies, and building material businesses to make informed decisions, but also reveals industry trends and business opportunities. This article provides the latest data, analyzes major regions, and highlights challenges and prospects in the global steel sector.
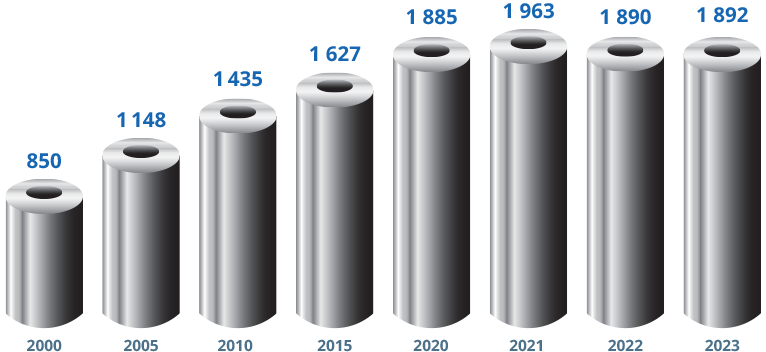
According to the World Steel Association (World Steel), global crude steel production reached approximately 1,892 million tonnes in 2023 and is projected to be around 1,885 million tonnes in 2024. This means that from 2020 onwards, global output has essentially moved sideways rather than entering a strong growth phase, with an average growth rate of only about 0.4% per year in the 2020–2023 period. In other words, while steel remains a core material for construction, infrastructure, manufacturing, and automotive industries, overall demand growth has been modest and highly sensitive to macroeconomic conditions, such as slower global GDP growth, tightening financial conditions, and disruptions in supply chains.
The near-flat trend also reflects contrasting regional dynamics. Mature markets such as Europe and some advanced economies in Asia have seen subdued or even declining steel consumption due to stagnant construction activity, energy price pressures, and ongoing transitions toward greener, more efficient production technologies. Meanwhile, emerging economies – particularly in Asia – continue to be the main drivers of demand, but their growth has not been strong enough to lift global production sharply above pre-2020 levels. Taken together, this plateau in crude steel output highlights a period of adjustment for the global steel industry: producers are under pressure not only to balance capacity with relatively modest demand growth, but also to invest in higher-quality, higher-value and more environmentally friendly steel products to maintain competitiveness in a changing market.
Asia accounts for the majority of global steel output. For instance, in 2024, the average steel consumption per person for new products was approximately 214.7 kg.
worldsteel.org
At the company level, crude steel production is highly concentrated in a small number of very large groups. For example, China Baowu Group currently leads the global industry, with output exceeding 130 million tonnes in 2024, according to data reported by the World Steel Association (worldsteel.org). This scale of production underlines not only Baowu’s dominant position in China’s domestic market, but also its strategic role in the global steel supply chain, alongside other major multinational steelmakers operating in Asia, Europe and the Americas.
Overall, the global steel industry appears to be in a production-stable phase rather than a strong growth cycle. Output is no longer rising rapidly, as it is being constrained by a combination of factors: a slowing global economy that dampens demand for construction and manufacturing, rising input costs (energy, raw materials, labour), and persistent excess capacity in several regions, particularly where past investments overshot actual demand. As a result, producers are under increasing pressure to focus less on expanding volume and more on optimizing efficiency, upgrading product quality, and shifting toward greener, higher-value steel solutions to remain competitive in this new, more mature stage of industry development.
According to Nippon Steel, total global finished steel consumption in 2021 was around 1,874 million tonnes, with a growth rate of approximately 5.8% compared to the previous year.
nipponsteel.com
More recent analysis from Steel on the Net estimates steel consumption in 2024 at around 1,793 million tonnes, with a forecast of 1,815 million tonnes for 2025.
Steelonthenet.com
Recent reports suggest the global steel industry may experience a slight recovery in 2026, with an estimated growth of ~1.3% according to World Steel.
Eurometal
End-use segments: Construction, automotive manufacturing, shipbuilding, and metal products are the major steel-consuming sectors.
Steelonthenet.com
Observation: Steel consumption faces pressure from slow economic growth, especially in major economies, resulting in modest growth.
China remains the world’s largest steel producer and consumer. Although China’s production is very high, it is showing signs of stabilization and even slight decline.
OECD
India is emerging as a fast-growing market for both steel production and consumption.
According to the European Steel Association (EUROFER), the steel industry in the EU generates approximately €215 billion in revenue with a production volume around 146 million tonnes/year.
However, Europe faces significant challenges from high energy costs, international competition, and global overcapacity.
Steel consumption in North America is recovering but growth remains modest.
Steelonthenet.com
Developing regions such as Southeast Asia, the Middle East, and Africa are projected to have stronger steel consumption potential in the future.
OECD
Excess capacity:
According to the Organisation for Economic Co-operation and Development (OECD), approximately 165 million tonnes of new steel capacity will be added between 2025 and 2027, mainly in Asia. This rapid expansion increases the risk of significant overcapacity, pushing utilization rates down to around 70%, which places strong pressure on pricing and profitability.
Energy & raw material costs:
Steel production is inherently energy-intensive and heavily dependent on key raw materials. As a result, rising costs of electricity, gas, coal, and iron ore directly erode profit margins and weaken competitiveness—especially for producers relying on traditional blast furnace operations.
Environmental pressure & the transition to green steel:
Steel manufacturing is one of the largest global sources of CO₂ emissions. Therefore, the transition toward “green steel” technologies—such as Electric Arc Furnaces (EAF), reducing coal dependency, and adopting hydrogen-based production—is becoming mandatory rather than optional. Technical reports and research, including publications on arXiv, emphasize that investment in cleaner technologies is now essential for long-term viability.
Demand from steel-consuming industries:
Steel demand is closely linked to sectors such as construction, real estate, and automotive manufacturing. Slowdowns or reduced growth in these industries can significantly affect steel consumption, leading to fluctuations in output and market prices.
International competition & trade policies:
Global competition in the steel industry is strongly shaped by government subsidies, low-priced steel exports, and trade defense measures such as anti-dumping tariffs. These factors, monitored closely by the OECD, continue to influence market structure and drive increasing differentiation among global producers.
Although global growth is slow, opportunities exist in developing markets such as India, Southeast Asia, and the Middle East, where infrastructure and construction demand is increasing.
Eurometal
Investing in clean steel production, recycled steel, and high-value steel products (premium grades, specialty steel) will enhance business competitiveness.
Steel producers and raw material suppliers can leverage the “green steel” and circular economy trends.
Supply chains and export markets should monitor trade policies and import/export tariffs due to increasing global competition.
The global steel industry is entering a stable but challenging phase: production growth is minimal, consumption increases slowly, while excess capacity and high input costs threaten profitability. However, opportunities remain if businesses understand trends and focus on growth markets, technological innovation, and product value enhancement.
For companies in the steel sector — from production and consumption to raw material supply — capitalizing on emerging markets and adopting greener production practices will be critical for long-term survival.